01Ground Reality: Two States in One, Stitched Together by Expressways
Uttar Pradesh is two property markets wearing one name. The first is the NCR slice: Noida, Greater Noida and Ghaziabad, which sit on Delhi's border, run on Delhi's salaries and account for the majority of the state's real estate value, its branded apartment supply and its office stock. The second is everything east of the Yamuna Expressway: Lucknow, the capital that has become a genuine second market; Kanpur, Agra, Varanasi, Prayagraj and Meerut as regional centres; and a long tail of district towns where property is a plot with a patta and a house built over ten years.
The money comes from four places. Delhi's corporate payroll and the IT and back-office campuses on the Noida Expressway and in Sector 62 buy and rent the NCR slice. Government, with the secretariat, the high court bench and two lakh state employees, plus the new IT and start-up layer, pays for Lucknow. Trade and manufacturing, leather in Kanpur, brass in Moradabad, sports goods in Meerut, glass in Firozabad, carpets in Mirzapur and Bhadohi, sugar across the west, buy kothis in the district towns. And pilgrims: Varanasi, Ayodhya, Mathura, Prayagraj and Gorakhpur are religious economies whose hospitality land has re-priced faster than any residential market in the state.
What changed in the last five years: the expressway grid got built, with the Purvanchal, Bundelkhand and Gorakhpur Link expressways joining the Yamuna and Agra–Lucknow ones and the Ganga Expressway nearing completion; Noida International Airport at Jewar went from a site to a terminal; the Ram temple at Ayodhya turned a district town into a land rush; the Delhi–Meerut RRTS started running; and Noida's Sector 150 and Greater Noida West filled up with the supply that the Amrapali and Jaypee collapses had frozen. UP RERA, the busiest in the country, became the forum where a decade of stalled projects is being settled.
The honest caution: Uttar Pradesh has more stranded homebuyers than any other state. Amrapali, Jaypee Infratech, Unitech, Supertech and a hundred smaller names left tens of thousands of families paying EMIs on towers that stopped in 2014. Many are now being completed through the NCLT and the Supreme Court-appointed processes, but the lesson stands: in UP you buy from a developer with occupation certificates in the same sector, or you buy ready.
02Location and Macro Infrastructure: The Expressway Grid, Jewar and the RRTS
No state has built roads the way Uttar Pradesh has in the last decade, and property values now follow the expressway map.
The expressway grid
- Yamuna Expressway. Noida to Agra, 165 km, open since 2012; YEIDA's sectors along it near Jewar are the state's largest plotted-land market, re-priced by the airport.
- Agra–Lucknow Expressway. 302 km through Firozabad, Etawah, Kannauj and Unnao; it made Lucknow a six-hour drive from Delhi and gave Etawah and Kannauj a reason to exist on investors' maps.
- Purvanchal Expressway. Lucknow to Ghazipur, 341 km, through Sultanpur, Azamgarh and Mau; the Lucknow side's Sultanpur Road and Gosainganj belt is priced on it.
- Bundelkhand Expressway. Chitrakoot to Etawah, 296 km, linking Jhansi's district to the Agra–Lucknow line and the planned BIDA industrial city.
- Ganga Expressway. Meerut to Prayagraj, 594 km, the state's longest, nearing completion; it runs through Hapur, Bulandshahr, Amroha, Badaun, Shahjahanpur, Hardoi, Unnao and Raebareli and puts Shahjahanpur and Hardoi on the map for logistics land.
- Gorakhpur Link, Delhi–Meerut and the Eastern Peripheral. The Delhi–Meerut Expressway cut Meerut to under an hour from Delhi; the Eastern Peripheral orbits Delhi through Ghaziabad and Greater Noida; the Gorakhpur Link joins Gorakhpur to the Purvanchal.
Airports
Noida International Airport at Jewar, in Gautam Buddh Nagar district on the Yamuna Expressway, is the largest infrastructure project in north India and the reason YEIDA plots, Greater Noida West and Faridabad across the river have been re-priced. Lucknow's Chaudhary Charan Singh airport has a new terminal and international routes; Varanasi, Ayodhya, Gorakhpur, Kanpur, Agra, Prayagraj and Bareilly have scheduled domestic service, and the Ayodhya and Varanasi airports are pilgrim gateways in their own right.
Rail, metro and RRTS
The Delhi–Meerut RRTS, India's first regional rapid rail, runs through Ghaziabad, Modinagar and Meerut and has re-priced every station it touches; Meerut's own metro shares the line. Noida's Aqua Line, the Delhi Metro's Blue Line to Noida City Centre and Sector 62 and the Red Line into Ghaziabad serve the NCR slice. Lucknow Metro runs north to south through the city with an east–west line planned; Kanpur Metro is open in part; Agra's is under construction. Varanasi's ropeway is the pilgrim-transit experiment. The Eastern Dedicated Freight Corridor runs through the state from Saharanpur to Mughalsarai, which is why Khurja, Kanpur's Bhaupur and Dadri are logistics-land stories.
03Micro-Markets and What Sells: City by City
Twenty-eight cities, five tiers. Rates are indicative asking prices from recent deals and listings; the NCR slice quotes flats by the sq ft and plots by the sq m or sq yd, the rest of the state quotes plots by the sq yd and farmland by the bigha.
| City | Tier | What actually sells | Indicative rates (current) |
|---|---|---|---|
| Noida (NCR) | 1 | Apartments, penthouses, studios, authority plots, Grade A offices, co-working, high-street shops | Flats ₹7,000–18,000/sq ft by sector; plots ₹1.5–4 lakh/sq yd |
| Greater Noida (NCR) | 1 | Greater Noida West apartments, YEIDA and GNIDA plots, villas, institutional and industrial land | Flats ₹5,500–9,000/sq ft; YEIDA plots ₹40,000–90,000/sq yd |
| Ghaziabad (NCR) | 1 | Apartments in Indirapuram, Vaishali, Raj Nagar Extension and Crossings; builder floors; industrial sheds | Flats ₹4,500–10,000/sq ft; plots ₹60,000–2 lakh/sq yd |
| Lucknow | 2 | Apartments, LDA plots, villas in gated townships, builder floors, showrooms, offices, farmhouses | Flats ₹4,500–9,000/sq ft; plots ₹40,000–1.5 lakh/sq yd |
| Kanpur | 2 | Flats, KDA plots, kothis, industrial sheds, warehouses | Flats ₹3,500–6,500/sq ft; plots ₹30,000–1 lakh/sq yd |
| Agra | 2 | Flats, plots, kothis, hotel land on Fatehabad Road, Taj-zone-compliant industry | Flats ₹3,500–6,000/sq ft; plots ₹25,000–80,000/sq yd |
| Varanasi | 2 | Flats, plots, hotels and guest houses, ring-road warehousing | Flats ₹4,000–7,000/sq ft; plots ₹25,000–90,000/sq yd |
| Prayagraj | 2 | Flats, PDA plots, kothis in Civil Lines, Kumbh hospitality | Flats ₹3,500–6,000/sq ft; plots ₹25,000–80,000/sq yd |
| Meerut | 2 | Flats, MDA plots, builder floors, sports-goods sheds, RRTS-side land | Flats ₹3,500–6,000/sq ft; plots ₹30,000–90,000/sq yd |
| Bareilly | 3 | Plots, builder floors, showrooms, farm land | Plots ₹20,000–60,000/sq yd |
| Aligarh | 3 | Plots, AMU-area rentals, lock-industry sheds, defence-corridor land | Plots ₹15,000–50,000/sq yd |
| Moradabad | 3 | Plots, exporter kothis, brass sheds | Plots ₹15,000–50,000/sq yd |
| Gorakhpur | 3 | Plots, builder floors, GIDA industrial plots, AIIMS-side rentals | Plots ₹20,000–60,000/sq yd |
| Saharanpur | 3 | Plots, houses, wood-carving sheds, highway commercial | Plots ₹15,000–45,000/sq yd |
| Jhansi | 3 | Plots, houses, cantonment rentals, BIDA and defence-corridor land | Plots ₹10,000–35,000/sq yd |
| Ayodhya | 3 | Plots, hotels, dharamshalas, ring-road and airport-side land | Plots ₹20,000–80,000/sq yd; far more near the corridor |
| Mathura | 3 | Plots, pilgrim hospitality, Vrindavan second homes, expressway land | Plots ₹15,000–60,000/sq yd |
| Muzaffarnagar | 4 | Plots, houses, cold storage, sugar-belt land | Plots ₹12,000–40,000/sq yd |
| Shahjahanpur | 4 | Plots, houses, Ganga Expressway warehousing | Plots ₹8,000–25,000/sq yd |
| Firozabad | 4 | Plots, houses, glass-industry sheds | Plots ₹8,000–25,000/sq yd |
| Rampur | 4 | Plots, houses, cold storage | Plots ₹8,000–25,000/sq yd |
| Farrukhabad | 4 | Plots, houses, cold storage, agricultural land | Plots ₹6,000–20,000/sq yd |
| Kasganj | 5 | Plots, houses, farm land | Plots ₹5,000–15,000/sq yd |
| Lakhimpur | 5 | Plots, houses, sugar and Dudhwa tourism land | Plots ₹6,000–18,000/sq yd |
| Hapur | 5 | Plots, houses, expressway commercial | Plots ₹10,000–30,000/sq yd |
| Etawah | 5 | Plots, houses, expressway commercial | Plots ₹6,000–20,000/sq yd |
| Mirzapur | 5 | Plots, houses, carpet sheds, pilgrim hospitality | Plots ₹6,000–20,000/sq yd |
| Amroha | 5 | Plots, houses, farm land | Plots ₹6,000–18,000/sq yd |
Noida
Noida is an authority city: every plot is a 90-year lease from the Noida Authority, which sets the sector plan, the floor area and the transfer rules. Sector 150 on the Expressway's southern end is the current premium address at ₹12,000 to 18,000 per sq ft, with Godrej, Tata, ATS and the sports-city townships. Sectors 75 to 79, Central Noida, are the mid-premium belt at ₹10,000 to 14,000. The Expressway sectors 93 to 137 carry Jaypee's legacy, the completed towers and the ones still in the NCLT. Sectors 44 to 50 and 61 to 62 are the old established flats and the IT campuses; Sectors 15A, 30, 36 and 44 are the plotted kothi belt where land trades at ₹2 to 4 lakh per sq yd. Grade A offices line the Expressway and Sector 62; the Film City and the data-centre cluster in Sectors 140 to 145 are the next employment layer. Buyers are Delhi corporate families, IT and media professionals and investors from across the state.
Greater Noida and the Yamuna Expressway
Greater Noida West, the Noida Extension sectors along the Hindon, is the NCR's biggest affordable apartment market at ₹5,500 to 9,000 per sq ft, with a metro link approved and the farmers' compensation disputes that froze it a decade ago now mostly settled. The GNIDA sectors, Alpha to Zeta and the Pari Chowk belt, are plotted and institutional, with Gautam Buddha University, the Expo Mart and the Jewar-bound traffic. The YEIDA sectors 17 to 22 along the Yamuna Expressway are the plotted-land market the airport created: authority plots at ₹40,000 to 90,000 per sq yd and rising with every flight announcement, plus the industrial and logistics allotments, the Film City and the semiconductor and electronics parks.
Ghaziabad
Indirapuram and Vaishali are Delhi-adjacent established apartment localities at ₹7,000 to 10,000; Raj Nagar Extension is the volume affordable market at ₹4,500 to 6,500; Crossings Republik and the NH-24 belt sit between them; Kavi Nagar, Raj Nagar and Nehru Nagar are the plotted kothi sectors. The Delhi–Meerut Expressway, the RRTS stations at Sahibabad, Ghaziabad and Duhai and the Hindon civil airport are the catalysts; the Hindon floodplain and the industrial-area air are the trade-offs.
Lucknow
Lucknow has become the state's second real market. Gomti Nagar and its Extension are the premium belt at ₹6,000 to 9,000 per sq ft with the high court, the IT city and Lulu Mall; Shaheed Path, Sultanpur Road and the Purvanchal link are the growth corridor where Omaxe, Eldeco, Ansal's Sushant Golf City, Emaar and Shalimar's townships sell at ₹4,500 to 7,000; Hazratganj, Mahanagar and Aliganj are the old city and the LDA's older colonies; Raebareli Road and Kanpur Road are the affordable plotted edge. LDA and Awas Vikas plots are the clean titles; the unauthorised colonies on the Faizabad Road and Sitapur Road fringe are the trap. Buyers are the state's officers and lawyers, the IT and services layer, NRIs from the Awadh belt and investors from across eastern UP.
Kanpur, Agra, Varanasi, Prayagraj, Meerut
Kanpur is Swaroop Nagar, Kakadeo, Arya Nagar and the Kalyanpur–bypass townships for housing and Panki, Chakeri and the Jajmau leather belt for industry, with the metro and the defence corridor's Kanpur node as catalysts. Agra is Fatehabad Road's hotel strip, Sikandra and Dayal Bagh for housing, and a Taj Trapezium Zone that caps polluting industry and keeps the city's economy in tourism, footwear and the expressways. Varanasi is Sigra, Lanka and the Sarnath side for flats, the ghats and the Kashi Vishwanath corridor for hospitality, and the ring road for warehousing; the pilgrim boom has re-priced guest-house land more than anything residential. Prayagraj is Civil Lines and the high-court belt, with the Kumbh every twelve years as the hospitality cycle. Meerut is Shastri Nagar, the Garh Road side and the MDA's new sectors, priced on the RRTS and the Ganga Expressway's start.
Ayodhya and Mathura: the pilgrim land markets
Ayodhya is the state's most dramatic re-pricing: the Ram temple, the airport, the ring road and the greenfield township turned a sleepy district town into a market where plots near the corridor trade at multiples of their circle rate and hotel land has national bidders. Buy only with a clear ADA patta and a registered deed; the town's land disputes predate the temple. Mathura and Vrindavan run on the Banke Bihari corridor, the Yamuna Expressway and Delhi devotees buying second homes; the rules on building near the temples are tightening.
The Tier-3 towns
Gorakhpur is eastern UP's rising market on AIIMS, GIDA, the link expressway and the airport. Aligarh has AMU, the lock industry and a defence-corridor node an hour from Jewar. Bareilly, Moradabad and Saharanpur are trading and export towns with plotted markets on their arterial roads. Jhansi is Bundelkhand's centre with the expressway, the cantonment and the planned BIDA industrial city.
Who buys, and in what bracket
- Under ₹50 lakh: Greater Noida West and Raj Nagar Extension 2 BHKs, Lucknow's Raebareli Road flats, Tier-3 to Tier-5 plots; first-time buyers, factory and trade families.
- ₹50 lakh to ₹1.5 crore: Noida Sectors 75 to 79 and Expressway 3 BHKs, Indirapuram, Gomti Nagar and Shaheed Path flats, Kanpur, Varanasi and Meerut townships, YEIDA plots; the NCR salaried class, state officers, NRIs.
- ₹1.5 crore to ₹5 crore: Sector 150 and Central Noida premium towers, Gomti Nagar villas, Lucknow and Kanpur kothis, Agra and Varanasi hotel land; business families, senior professionals, investors from across the state.
- Above ₹5 crore: Noida's plotted kothi sectors, Sector 150 penthouses, Gomti Nagar Extension estates, Ayodhya and Varanasi corridor hospitality; promoters, politicians and HNIs.
04Industry and Employment: What Pays the EMIs
The NCR slice: IT, media, electronics and offices
Noida's Sector 62 and the Expressway campuses house HCL, Samsung's largest mobile plant, Paytm, Adobe, Barclays, Genpact and the media district of Sector 16 to 18; the Sectors 140 to 145 data-centre cluster and the YEIDA electronics and semiconductor parks are the next layer. Ghaziabad's Sahibabad and Bulandshahr Road industrial areas, Greater Noida's Surajpur and Ecotech estates and the Dadri logistics node round it out. This is the salaried base that rents and buys the NCR slice.
Lucknow: government, IT and the start-up layer
The secretariat, the high court bench, the state's public-sector offices and two lakh government employees are Lucknow's base; HCL, TCS and the IT city, the Awadh belt's professionals and a growing start-up and hospitality economy sit on top. Lucknow is also the state's medical hub, with SGPGI, KGMU and the private chains.
The manufacturing and craft belts
Kanpur's leather, textiles and defence ordnance plus the UP Defence Industrial Corridor's Kanpur and Lucknow nodes; Moradabad's brass exports; Meerut's sports goods and scissors; Firozabad's glass; Aligarh's locks; Saharanpur's wood carving; Mirzapur and Bhadohi's carpets; Agra's footwear; the sugar mills of the west; Gorakhpur's GIDA estate; Jhansi's defence node and the planned BIDA city. Each is an owner-run economy that builds kothis and rents rooms.
Pilgrimage and tourism
Varanasi, Ayodhya, Mathura–Vrindavan, Prayagraj and Gorakhpur draw pilgrims in the hundreds of millions a year, and Agra is India's most visited monument city. Hotels, dharamshalas, guest houses and the pilgrim-transport chain are the largest private employer in those cities and the basis of their hospitality land markets.
Agriculture and logistics
Sugar, wheat, rice, potatoes and dairy make UP India's largest agricultural economy; the expressway grid and the Eastern Dedicated Freight Corridor are turning Dadri, Khurja, Kanpur, Shahjahanpur and the Varanasi ring road into warehousing markets. UPSIDA is the industrial land authority outside the NCR authorities, with estates in every district; its plots and the NCR authorities' industrial allotments are leasehold with transfer charges. The single window is Nivesh Mitra.
05What Changes in the Next 3 to 7 Years
- Noida International Airport at Jewar opening and scaling. The strongest catalyst in the state. YEIDA plots, Greater Noida, Sector 150 and the Expressway, Aligarh, Mathura and Faridabad across the river all re-price as flights begin and the Film City, logistics and electronics parks around it fill.
- Ganga Expressway completion. Meerut to Prayagraj in six hours puts Hapur, Amroha, Badaun, Shahjahanpur, Hardoi and Unnao on the logistics map and gives Prayagraj a second corridor.
- Delhi–Meerut RRTS fully operational and the Noida and Ghaziabad metro extensions, including the Greater Noida West line; every station is a micro-market event.
- Lucknow's growth corridor: the Purvanchal link, the metro's east–west line, the IT city's expansion, the planned new townships on Sultanpur Road and the Kanpur–Lucknow expressway that makes the two cities one market.
- The UP Defence Industrial Corridor at Aligarh, Agra, Jhansi, Kanpur, Lucknow and Chitrakoot, and BIDA, the new industrial city near Jhansi, for industrial land and worker housing.
- Ayodhya, Varanasi and Mathura's pilgrim infrastructure: airports, ring roads, corridors and townships that keep hospitality land re-pricing, within tightening rules on what may be built near the shrines.
- Stalled-project resolution. As Amrapali, Jaypee and Supertech towers get completed through the courts and the NCLT, a large block of frozen supply returns to Noida and Greater Noida, which caps price growth in the mid-market and restores liquidity.
- Circle-rate revisions and the authority dues settlement. Noida and Greater Noida revised circle rates upward and the Supreme Court's settlement of builders' land dues unlocked registries that had been stuck for years.
What this means for appreciation: Noida's Sector 150 and Central Noida have priced in Jewar and will track Delhi's cycle; Greater Noida West and the YEIDA sectors have the most headroom but also the most supply. Lucknow's Shaheed Path and Sultanpur Road belt is the best risk-adjusted growth story in the state. The pilgrim cities are hospitality plays, not residential ones. The district towns move with sugar prices, exports and the nearest expressway interchange.
06Civic Life: Hospitals, Universities, Malls and What Breaks
Healthcare
SGPGI, KGMU, Medanta and Apollo in Lucknow; Fortis, Max, Jaypee and Yatharth in Noida; AIIMS Gorakhpur and the AIIMS satellites; BHU's hospital in Varanasi; the medical colleges in Kanpur, Agra, Meerut, Prayagraj and Jhansi. Lucknow and Noida are where the state's serious cases go; the rest drive to them or to Delhi.
Education
IIT Kanpur, IIT BHU, IIM Lucknow, AMU, BHU, Lucknow University, the Jewar-side and Greater Noida university belt with Gautam Buddha University, Amity, Sharda and Galgotias, Shiv Nadar University and the Noida international schools; Dehradun-style boarding schools do not exist here, but the Lucknow and Noida school belts are a reason families buy in those cities.
Retail and recreation
DLF Mall of India and the Great India Place in Noida, Lulu and Phoenix Palassio in Lucknow, Z Square in Kanpur, the Sarnath and ghat circuits in Varanasi, the Ekana cricket stadium in Lucknow and the Noida sports complexes; the Noida Film City, Lucknow's Hazratganj and the Gomti riverfront are the leisure anchors.
The civic realities
- Air: Noida, Ghaziabad and Meerut sit inside the NCR's winter smog with AQI above 400 for weeks; Lucknow, Kanpur and Agra are not far behind. Ghaziabad regularly tops national lists.
- Water: Noida and Greater Noida depend on Ganga canal water and borewells with summer tankers; Lucknow's Gomti Nagar runs on groundwater that is falling; Agra and the Bundelkhand towns ration in May.
- Drainage: Noida's Sector 150 and Expressway underpasses, Greater Noida West's Hindon floodplain, Ghaziabad's Indirapuram and Lucknow's Gomti-side colonies flood in heavy monsoons; the 2023 Hindon floods are the reference event.
- Power: NCR authorities and Lucknow have reasonable supply; the district towns run on backup through the summer. Check the society's diesel charge per unit.
- Traffic: the Delhi–Noida border at DND and Chilla, the Noida Expressway at Sector 37, NH-24 through Ghaziabad, Lucknow's Polytechnic crossing and Kanpur's Rawatpur are the daily bottlenecks.
- Approvals and maintenance: authority townships in Noida and Greater Noida are supposed to hand over to residents' associations; many have not, and builder-resident maintenance fights are the commonest UP RERA complaint after delays. Unauthorised colonies on every city's fringe are demolished periodically by the development authorities.
07Climate and How to Build for It
Uttar Pradesh is the Gangetic plain: hot, humid, wet and foggy in turn, with the Bundelkhand south drier and hotter and the Terai north wetter.
Summer runs April to June with 42 to 47°C across the plain and the loo wind from the west; Jhansi, Agra and Prayagraj are the hottest. Monsoon is late June to September, 700 to 1,000 mm across most of the state, over 1,200 mm in the Terai and Gorakhpur belt, and under 800 mm in Bundelkhand; it comes in bursts that flood the Hindon, the Gomti and the eastern rivers. Winter from December to February brings 4 to 8°C nights, dense fog that shuts airports and the expressways for days, and the NCR smog season from late October.
What it means for a buyer or builder
- Insulated roofs, cavity or AAC walls and north or east-facing living spaces decide power bills; a west-facing Noida tower flat in June runs the air-conditioning sixteen hours a day.
- In the floodplain pockets, Greater Noida West, Ghaziabad's Hindon side, Lucknow's Gomti colonies and Varanasi's lower ghats, check the plinth height and the drainage; basements and stilt parking there are liabilities.
- Terrace waterproofing and external-wall sealing matter more than finishes; the humidity and the dust strip cheap exteriors in three seasons.
- Air purification and sealed windows are now selling features in Noida and Lucknow towers; check whether the system actually runs.
- Fog means the winter drive to Jewar or IGI takes longer than any app says; for a frequent flyer, Expressway and airport proximity is worth paying for.
- Rooftop solar pays back in both halves of the year; UP's net-metering has improved and the sun is reliable.
08Landmarks, Tourism and the Hospitality Angle
Uttar Pradesh is the heart of Indian pilgrimage and home to India's most visited monument, and hospitality land here re-prices faster than housing.
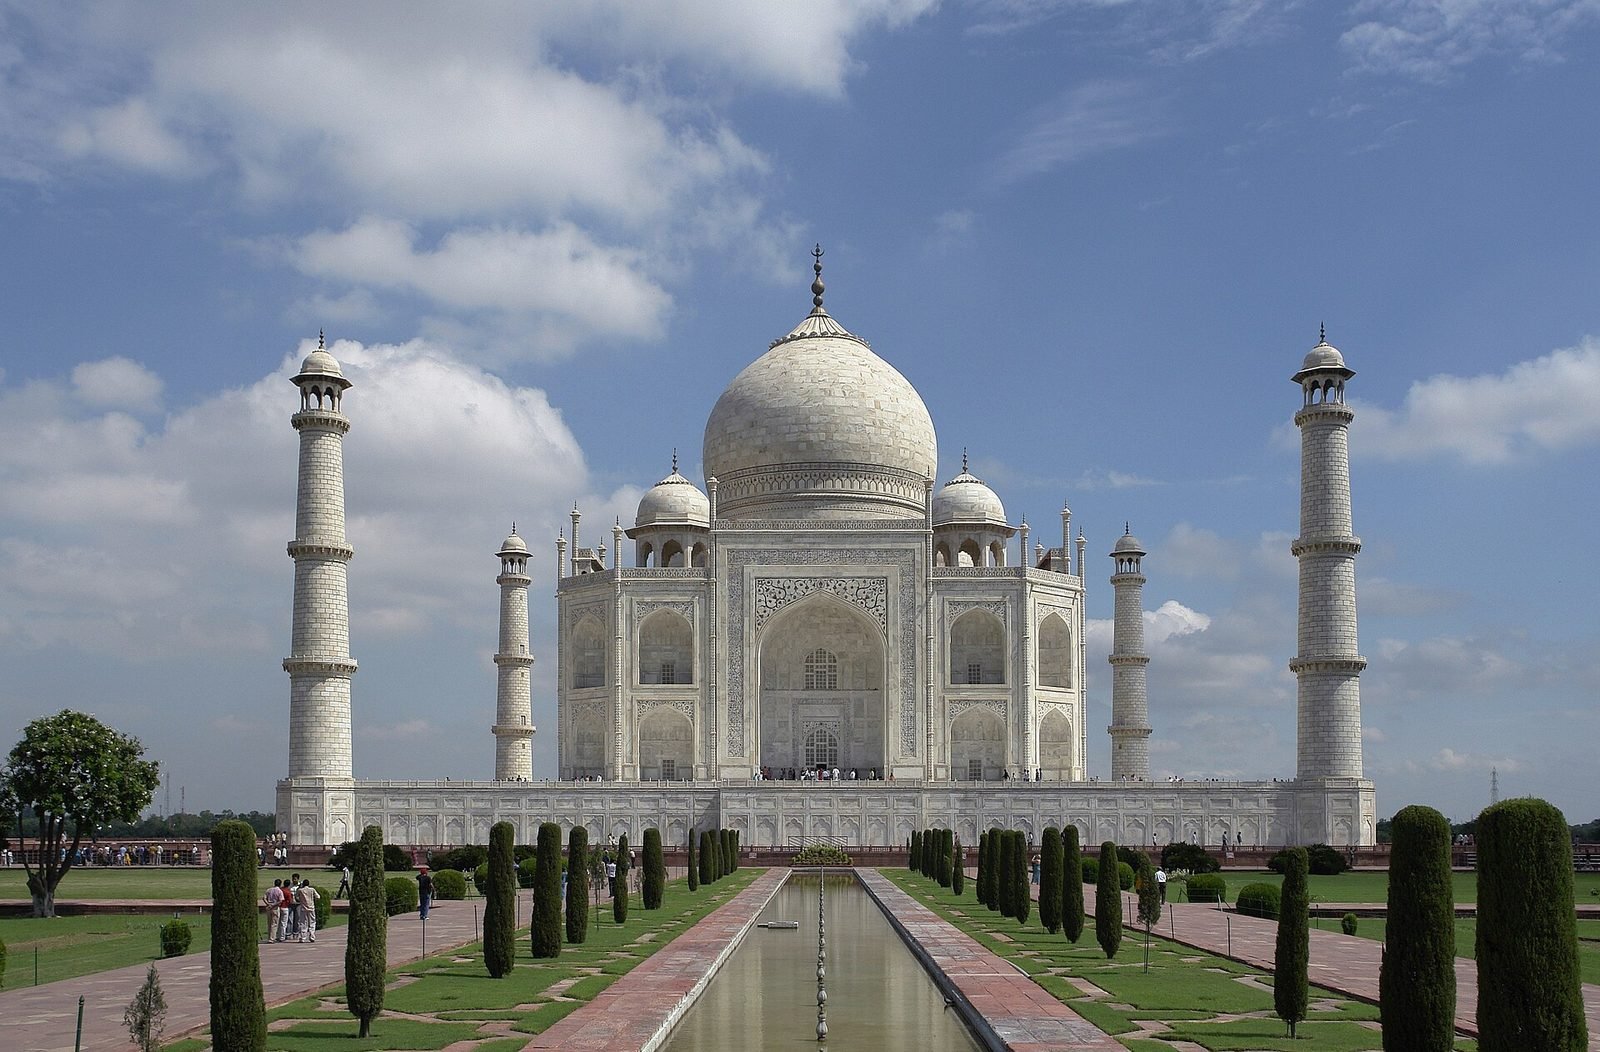
- Agra: the Taj Mahal, Agra Fort, Fatehpur Sikri and Sikandra; the Fatehabad Road hotel strip and the Taj Trapezium Zone rules that shape what may be built.
- Varanasi: the ghats, the Kashi Vishwanath corridor, Sarnath and the Ganga aarti; guest houses, hotels and the ropeway-era hospitality boom.
- Ayodhya: the Ram temple, Hanuman Garhi, the Saryu ghats and the greenfield township; the state's most intense hospitality land market.
- Mathura and Vrindavan: the Krishna circuit, Banke Bihari and Prem Mandir; dharamshalas, hotels and Delhi devotees' second homes on the Yamuna Expressway.
- Prayagraj: the Sangam and the Kumbh, Anand Bhavan and the high court; a twelve-year hospitality cycle with a permanent legal-city economy underneath.
- Lucknow: the Bara Imambara, Rumi Darwaza, the Residency, Hazratganj and the Awadhi food trail; heritage boutique hotels and a wedding economy.
- Gorakhpur, Sarnath, Kushinagar and Shravasti: the Buddhist circuit with international pilgrims and the Kushinagar airport.
- Dudhwa, the Chambal and Etawah's Lion Safari: the wildlife and river circuits with small resort markets.
The practical takeaway: Varanasi, Ayodhya and Mathura hospitality land are the liquid plays, driven by pilgrim numbers that keep rising; Agra is mature and zoned; Lucknow's heritage and wedding economy is the quiet one. Everything on the Buddhist and wildlife circuits is a long hold on footfall.
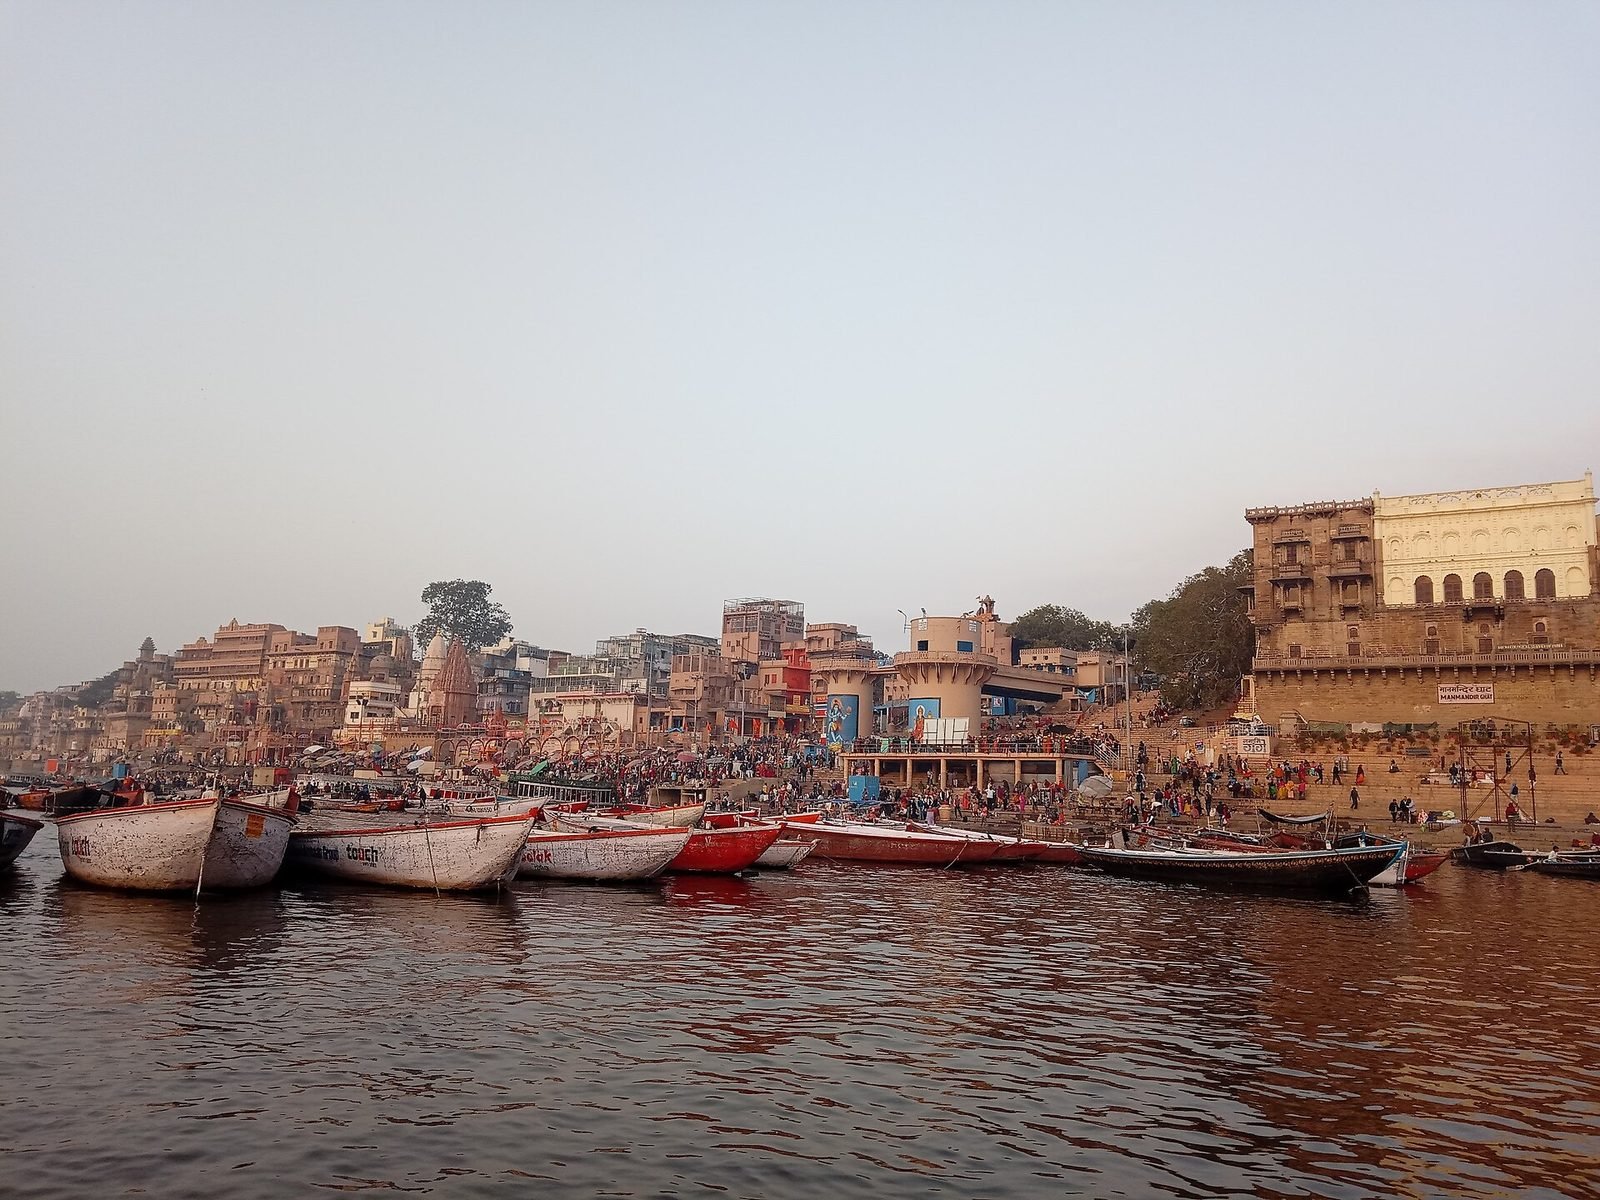
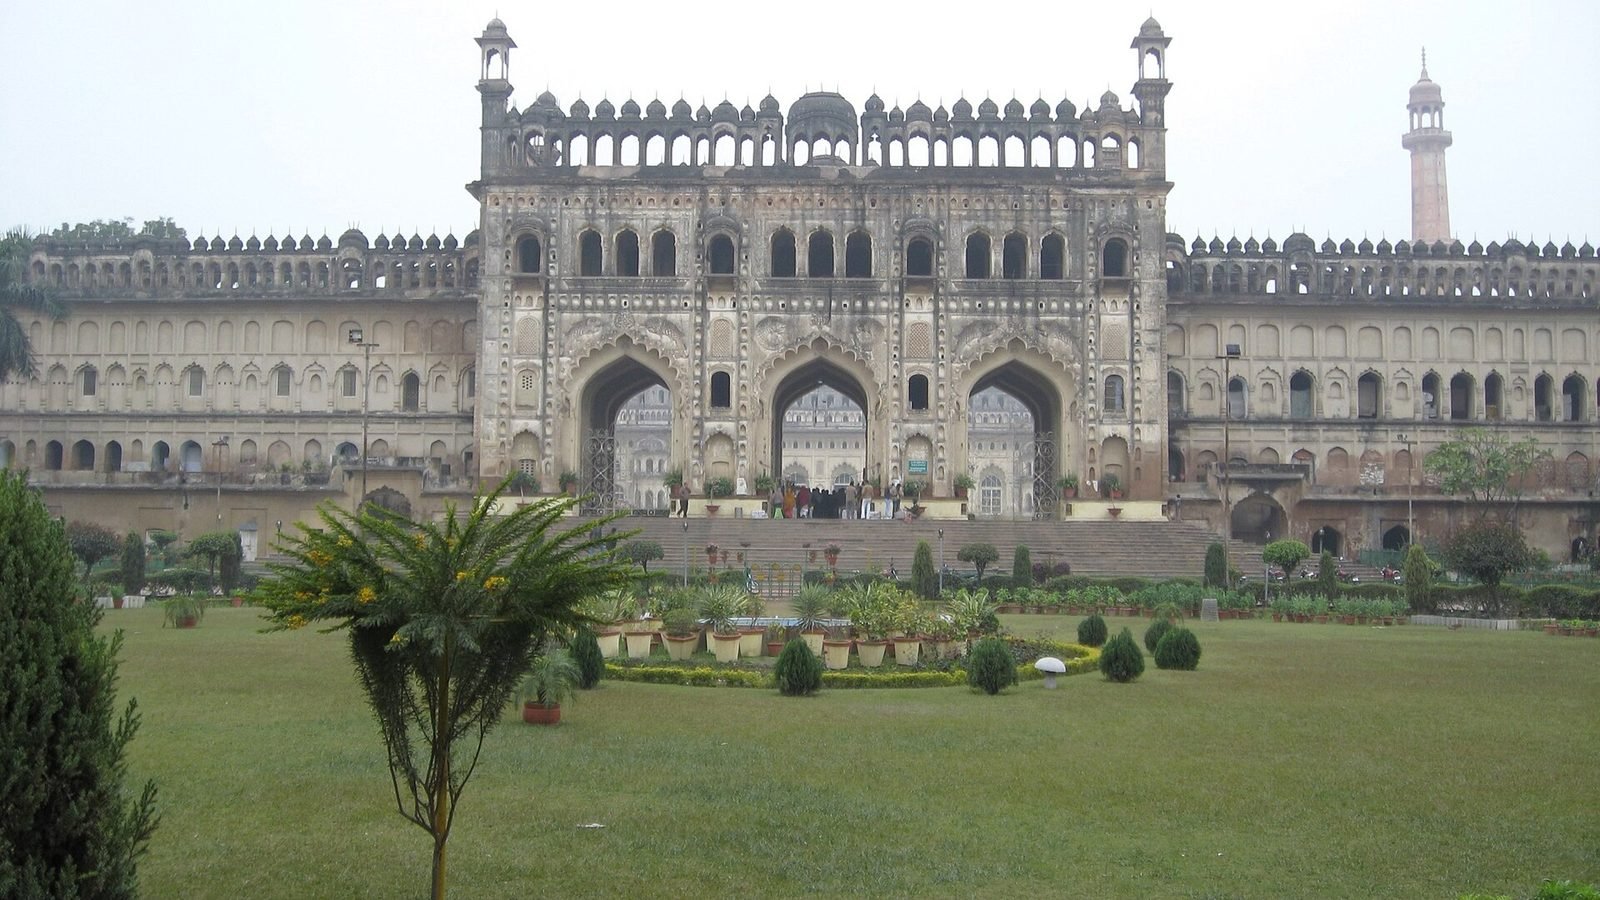
Photos: Kasyap, CC BY-SA 4.0, via Wikimedia Commons · Slyronit, CC BY-SA 4.0, via Wikimedia Commons · Divyendu Raj Sharma, CC BY-SA 4.0, via Wikimedia Commons
09Legal Checks, Stamp Duty and Property Tax: Uttar Pradesh Specifics
Uttar Pradesh paperwork differs sharply between the NCR authority cities and the rest of the state. The losses come from unregistered towers, authority dues, unauthorised colonies and farmland sold as plots.
Who approves what
In the NCR slice, the Noida, Greater Noida and Yamuna Expressway authorities own the land, allot it on 90-year leases, sanction plans and issue completion certificates; a flat's title runs through the builder's lease deed with the authority and your sub-lease, and a transfer needs the authority's transfer memorandum and the builder's no-dues. Elsewhere, the development authorities, LDA in Lucknow, KDA in Kanpur, ADA in Agra and Ayodhya, VDA, PDA, MDA, GDA in Gorakhpur and the rest, sanction layouts and plans, and Awas Vikas Parishad builds its own schemes. UPSIDA allots industrial land. UP RERA, with benches in Lucknow and Greater Noida, registers projects above the usual thresholds and is where delayed-possession complaints are fought. Land records live on the Bhulekh portal with the khasra and khatauni.
The due-diligence checklist
- UP RERA registration with the quarterly filings and the promoter's complaint record; in Noida and Greater Noida, check the authority's list of builders with unpaid land dues, because dues block registries.
- Authority lease deed and sanctioned plan for the project, and the completion or occupation certificate before you move in; a tower without one cannot be registered or mortgaged.
- Transfer memorandum and no-dues from the authority and the builder for any NCR resale flat or plot.
- Khatauni and khasra on Bhulekh for plotted land outside the NCR, with the mutation in the seller's name and no nazul, gram sabha or ceiling-surplus land in the number.
- Section 80 declaration under the UP Revenue Code converting agricultural land to non-agricultural use before you buy a "plot" carved from farmland; without it the development authority will not sanction a plan and the colony is unauthorised.
- Development-authority layout approval for private colonies and the authority's unauthorised-colony list, which LDA, KDA and ADA publish and act on.
- Encumbrances and litigation through a sub-registrar search and a court check; in Ayodhya, Varanasi and Mathura, check the shrine-corridor acquisition maps and the heritage-zone building limits.
- Taj Trapezium Zone and eco-sensitive-zone status for anything in Agra, Mathura and Firozabad districts.
Freehold, leasehold and agricultural land
Noida, Greater Noida and YEIDA property is leasehold from the authority for 90 years with lease rent and transfer charges; the authorities have discussed freehold conversion for years without delivering it. LDA, KDA and the other development authorities sell freehold; Awas Vikas schemes are freehold after the final allotment. Anyone can buy agricultural land in UP within the ceiling of about 12.5 acres per family; NRIs and OCIs cannot buy agricultural land, plantations or farmhouses under FEMA. Nazul land in Lucknow, Prayagraj and other old cities is government land held on expiring leases, and its renewal and freehold rules are a live political issue; a nazul title needs specialist advice.
Stamp duty and registration
Stamp duty in Uttar Pradesh is about 7 percent, with a 1 percent rebate for women buyers on properties up to a value cap, plus a 1 percent registration fee; the state has added concessions for family transfers and for some affordable categories. Duty is charged on the higher of the sale price and the circle rate, which Noida, Greater Noida, Lucknow and Ayodhya revised sharply upward recently. The authorities also collect transfer charges on NCR resales. Confirm the live figures before you budget; the state changes them by notification.
Property tax
Municipal property tax in Lucknow, Kanpur, Agra, Varanasi and the other corporations is self-assessed on annual rental value and is modest; in Noida and Greater Noida there is no municipal property tax yet, but the authority's lease rent and the society's maintenance, often ₹2 to 4 per sq ft a month in the newer towers, are the recurring costs that matter. The district towns pay nominal nagar palika tax.
Units you will hear
The NCR authorities quote plots in sq m; the rest of the state quotes plots in sq yd or gaj and farmland in bigha, and the UP bigha varies by district between about 1,000 and 3,000 sq yd. Flats are quoted in sq ft of super built-up area, and the circle rate is per sq m; convert everything before you compare.
Rates on this page are indicative asking prices gathered from transactions and listings Mr. Homez handled or reviewed. They change with every quarter and every collector-rate revision. Stamp duty, cess and tax rules are summarised from government notifications current at the time of writing; confirm the live figures with the sub-registrar before you commit money. This is market commentary, not legal or investment advice.